Eaton Q3 revenue hits $8.95 billion as data center demand surges 65%
The electrical equipment maker raised full-year guidance and reported record backlog figures, driving shares up nearly 7% on Tuesday.
By Omar Bennett ·
Eaton Corp. shares climbed almost 7% in afternoon trading on Tuesday to reach $391, capping a session where the company reported record third-quarter revenue of $8.95 billion. The figure, which covers the quarter ended Sept. 30, marked a 28% year-over-year increase and exceeded the LSEG consensus estimate of $8.51 billion. Adjusted earnings per share rose 20% to $3.68, beating the expected $3.54.
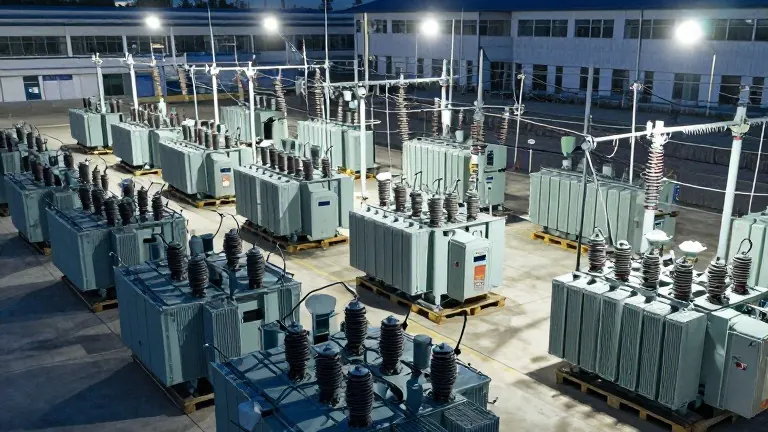
The strong performance was driven largely by demand for electrical infrastructure in data centers. Revenue in that specific sector jumped 65% year-over-year. CEO Paulo Ruiz stated that continued strength across end markets, combined with a record backlog, provides strong visibility into the company's outlook. He noted that this marks the third time Eaton has raised both organic and adjusted EPS guidance this year.
Management raised its full-year organic growth forecast to a range of 13% to 15%, up from the previous 11% to 13%. The adjusted EPS forecast was also boosted to $13.70 to $13.80 per share, surpassing the LSEG estimate of $13.61. For the fourth quarter, the company projects organic growth of 13% to 15% and adjusted EPS of $4.05 to $4.15.
The acquisition of Boyd Thermal, which closed in March for $9.5 billion, contributed significantly to these results. Ruiz said the business delivered nearly triple-digit year-over-year growth. Eaton raised the full-year outlook for the Boyd unit by $100 million to $1.9 billion. The company attributes 31 percentage points of Electrical Global segment sales growth to the Boyd acquisition, with the remaining 27 percentage points coming from organic growth.
The Electrical Americas segment posted record sales and operating profit, with 22% organic growth. Backlog in this segment reached a record $16 billion, up 33% year-over-year. The book-to-bill ratio for this segment stood at 1.3 on a rolling 12-month basis, indicating that orders are coming in faster than they can be delivered. Ruiz said new manufacturing capacity is now translating into output and margin.
Across the electrical sector, the combined book-to-bill ratio reached 1.2, with total backlog increasing 46% to over $20 billion. Order growth in data centers for the electrical sector accelerated to over 100% on a rolling 12-month basis. Ruiz indicated that Eaton's tracking shows announced data center projects in the U.S. have reached 366 gigawatts, up from 307 gigawatts three months ago. He noted that current installed capacity stands at approximately 50 gigawatts.
The Aerospace segment missed revenue estimates for the second consecutive quarter, though operating profit exceeded consensus due to a stronger-than-expected margin. Revenue in this unit grew 11%, driven by a 6% organic increase and a 5% benefit from acquisitions. The Mobility segment outpaced expectations for sales and profit, with 9% organic revenue growth. Eaton plans to divest the Mobility unit in the first four months of 2027 via a Reverse Morris Trust transaction.
Shares of Eaton remain well below their August closing high of roughly $460. The company expects to update its long-term growth target for the Electrical Global segment next year. Currently, that target is 5% annual growth from 2026 to 2030. The Mobility separation is expected to increase the percentage of sales from data centers and distributed IT, which are currently about a third of the total portfolio.
Source: CNBC
More Business · Consumer Alerts · Report a business · Got a Story?